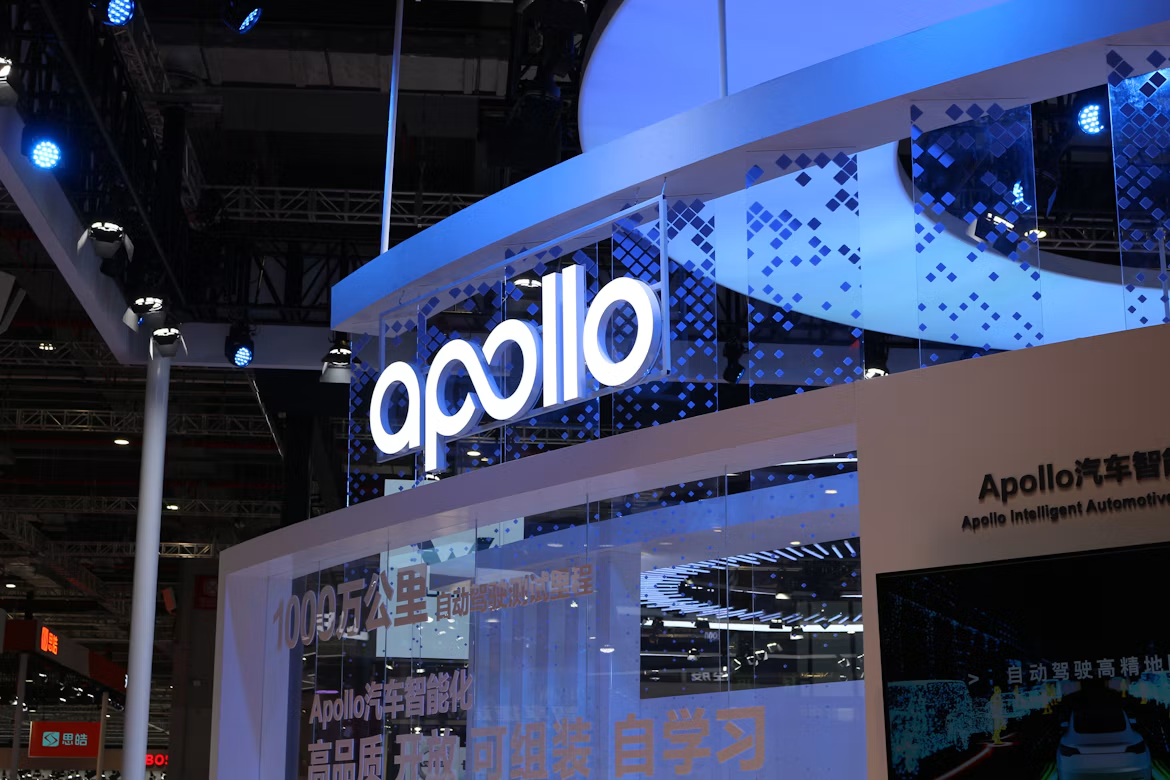
The bullish case for Baidu Inc. (NASDAQ:BIDU) rests on a business transformation that could become increasingly difficult for investors to overlook. Search advertising remains an important part of the company, but its investment appeal now extends into AI cloud infrastructure, the Ernie ecosystem, and enterprise applications. If those businesses contribute a growing share of earnings, investors could begin valuing Baidu more favorably as an AI technology provider.
That shift matters because advertising weakness can overshadow progress elsewhere in the business. Bulls see an opportunity for AI commercialization to establish a stronger growth engine while reducing the company’s dependence on an advertising recovery. The potential reward comes from two directions—higher earnings as AI services scale and a possible improvement in the valuation investors assign to those earnings.
AI Cloud Growth Provides a Concrete Foundation
Baidu’s cloud infrastructure business gives that argument measurable support. In the second quarter of 2026, AI Cloud Infra revenue reached RMB7.3 billion, increasing 50% year over year. Within that segment, GPU Cloud revenue climbed 283%, accelerating from 184% growth in the preceding quarter. These results demonstrate substantial demand for the computing resources businesses need to develop and deploy artificial intelligence.
For bulls, the attraction is the possibility that this demand develops into lasting customer relationships. An enterprise may initially purchase computing capacity for a limited project, then increase usage as AI becomes part of its regular operations. Under that scenario, Baidu could benefit from expanding workloads and recurring spending, giving its cloud business a more durable revenue base.
The earnings opportunity depends on how efficiently Baidu serves that demand. Higher infrastructure utilization could help spread costs across more customer activity, although pricing competition and additional investment could limit the benefit. A convincing bullish outcome would therefore involve cloud growth translating into improving profitability alongside higher revenue.
Ernie Could Expand the Commercial Opportunity
The Ernie ecosystem adds another potential avenue for growth. Computing infrastructure gives Baidu an entry point into enterprise AI spending, while models and applications create opportunities to serve more of a customer’s technology needs.
Consider a business that initially uses Baidu’s cloud to support an AI project. If it subsequently adopts tools for customer service, document processing, or employee productivity, Baidu could capture additional spending from the same relationship. This is a potential commercial pathway rather than an assured outcome, but it explains why bulls look beyond infrastructure revenue alone.
The investment thesis becomes stronger if Baidu can demonstrate that customers find enough value in its services to keep using them and expand their purchases. Successful commercialization would help turn technical capabilities into a repeatable business model. It could also make the company’s growth less dependent on fluctuations in advertising budgets.
Stock Connect Adds a Potential Ownership Catalyst
Baidu, Inc. (NASDAQ: BIDU) gained another catalyst in September when its Hong Kong shares entered both the Shanghai-Hong Kong and Shenzhen-Hong Kong Stock Connect programs. The inclusion allows eligible mainland investors to trade those shares directly through the programs, broadening access to the company. Baidu said the development was expected to diversify its investor base and enhance share liquidity.
For the bullish thesis, broader access creates the possibility of additional investment demand as Baidu’s AI story develops. Investors who previously faced limitations in buying its Hong Kong shares now have another route to participate.
The effect on valuation remains conditional. Access alone does not produce earnings growth or guarantee buying interest. However, if stronger AI results coincide with a broader investor audience, improved operating performance could receive greater market recognition.
The Valuation Leaves Room for an Earnings-Driven Revaluation
Using the supplied figures, Baidu trades at approximately 19.1 times forward earnings, with average analyst upside potential of roughly 83.5%. That multiple requires a credible growth argument, particularly because it is among the higher valuations in this selection.
Bulls would argue that sustained AI expansion could make the valuation more compelling over time. If earnings grow while the share price remains relatively subdued, the effective earnings multiple becomes less demanding. If investors also gain confidence in the durability of that growth, a higher valuation could provide an additional source of upside.
The supplied count of 49 hedge fund holders indicates institutional participation, although ownership does not establish that the stock is undervalued. Likewise, the analyst upside estimate reflects expectations that can change. The stronger reason to consider the stock is the possibility that its future earnings become meaningfully larger and less dependent on its legacy business.
What Would Make the Bullish Thesis Work
The most persuasive bullish scenario for Baidu, Inc. (NASDAQ: BIDU) combines sustained cloud demand, broader adoption of enterprise AI services, and improving returns on infrastructure spending. Together, those developments could help offset advertising pressure and strengthen the company’s earnings outlook.
Execution remains the deciding factor. Baidu needs to convert AI demand into profitable growth while competing for customers and managing investment costs. But if it succeeds, the market could increasingly recognize a company with multiple commercial AI opportunities. For investors researching Chinese AI stocks, that potential shift—from promising technology to a stronger earnings base—is the central reason Baidu deserves attention.
YOU MUST READ THIS: 10 Cheap Stocks Reddit Investors Think Could Skyrocket
Disclosure: No material interests to disclose. This article was originally published on Global Market Bulletin.