First Solar Inc. (NASDAQ:FSLR) offers a bullish case centered on its domestic manufacturing footprint, contracted backlog, and the possibility that investors are assigning too steep a discount to future earnings. Based on the supplied figures, the stock trades at approximately 8.3 times forward earnings, while average analyst price targets imply around 60.3% upside from the share price of $178.79. That combination makes it a compelling candidate for investors examining undervalued solar stocks.
The central argument is that the company could deliver the earnings already anticipated by analysts while gradually improving confidence in their durability. If that happens, the shares could benefit from both operating performance and a higher valuation multiple. A business does not necessarily need spectacular growth to produce meaningful stock upside when its starting valuation is modest.
However, the forward P/E relies on estimated earnings. The opportunity becomes more convincing if reported profits and updated guidance support those expectations. For First Solar, Inc. (NASDAQ: FSLR), consistent execution would give investors a stronger reason to reconsider the discount.
Domestic Manufacturing Could Strengthen Its Competitive Position
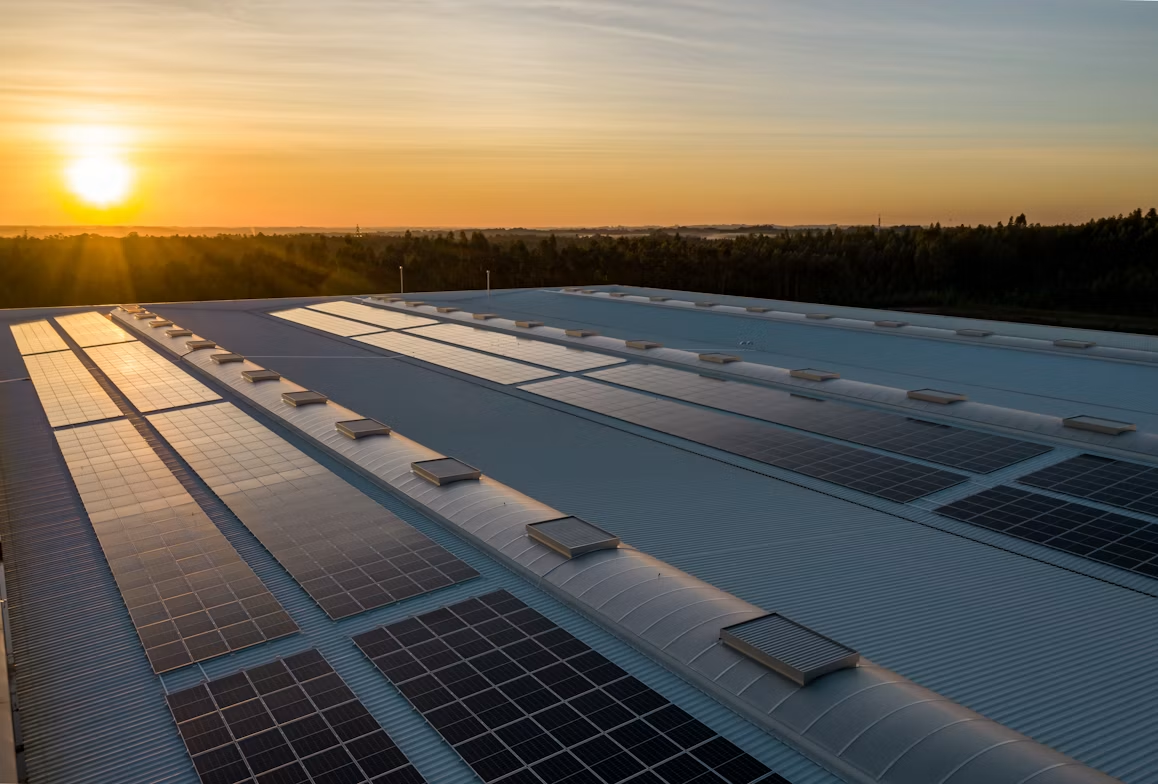
The domestic manufacturing footprint highlighted in the supplied coverage is an important part of the investment thesis. It gives First Solar, Inc. (NASDAQ: FSLR) an established production base from which to serve customers developing solar projects in the United States.
For project developers, confidence in equipment availability and delivery schedules can influence purchasing decisions. A domestic supplier could offer advantages where customers prioritize supply reliability or seek to reduce exposure to international shipping disruptions. Those advantages could help support demand, although their financial value ultimately depends on contract terms, production costs, and competitive pricing.
Clean-energy manufacturing incentives could also influence the economics of that footprint. The bullish scenario assumes the company can maintain attractive manufacturing returns under the policies that apply to its operations. Greater clarity around those incentives would make future earnings easier to evaluate and could reduce some of the uncertainty weighing on the shares.
A Contracted Backlog Provides a Foundation for Revenue Visibility
The contracted backlog gives First Solar, Inc. (NASDAQ: FSLR) a foundation for assessing future business activity. Existing customer commitments provide more visibility than relying entirely on orders that have yet to be secured.
That visibility can help the company plan production, manage capacity, and align deliveries with customer needs. If contracts translate into shipments on commercially attractive terms, the backlog could support revenue and earnings across future reporting periods. For shareholders, the crucial step is converting those commitments into realized profits and cash flow.
Backlog quality matters alongside its size. Delivery timing, customer readiness, and the profitability of individual contracts influence how much value reaches shareholders. The bullish case strengthens when the company demonstrates that its order book supports dependable earnings without persistent delays or margin pressure.
Better Project Financing Could Help Orders Move Toward Delivery
Interest rates remain an important influence on solar project economics because developers typically face substantial upfront investment. Higher borrowing costs can make projects harder to finance, affecting schedules even when customers remain interested in building them.
The constructive scenario is that financing conditions become more manageable, whether through lower borrowing costs, improved access to capital, or project economics that justify investment at prevailing rates. That could help developers advance projects and reduce uncertainty around equipment delivery schedules.
First Solar, Inc. (NASDAQ: FSLR) could benefit if more customers move from contracted plans into construction and installation. More predictable deliveries would make revenue recognition and production planning easier to manage. The resulting improvement in earnings visibility could matter as much to the stock as an increase in new orders.
Stronger Margins Would Make the Growth Story More Valuable
Demand for solar power creates an opportunity, but shareholder returns depend on the profits earned from supplying equipment. First Solar, Inc. (NASDAQ: FSLR) therefore needs to protect manufacturing economics as it fulfills customer commitments.
The bullish thesis assumes that the company can deliver products efficiently while maintaining a healthy relationship between selling prices and production costs. If shipments increase and costs remain controlled, a larger revenue base could support stronger operating earnings. Better production efficiency could provide additional upside if it allows the company to earn more from each unit delivered.
This is where the low forward valuation becomes particularly relevant. Evidence of resilient margins would make projected earnings more credible and could encourage investors to assign those earnings a higher multiple. Conversely, revenue growth with weakening profitability would offer less support for a sustained recovery.
Analyst Upside and Institutional Ownership Add Context
Average analyst price targets imply approximately 60.3% upside for First Solar, Inc. (NASDAQ: FSLR), suggesting a meaningful gap between the supplied market price and analysts’ average valuation. The September coverage also described continued bullish recommendations despite a sharp share-price decline.
That divergence creates an interesting investment debate. The market may be emphasizing financing and policy uncertainty, while bullish analysts may be placing greater weight on manufacturing capacity, contracted business, and expected earnings. The company’s subsequent results would help determine which assessment better reflects operating reality.
The reported 64 hedge fund holders in Q2 2026 provide an additional measure of institutional participation. That count does not establish whether funds were increasing their stakes, but it shows that the company featured in a substantial number of hedge fund portfolios during the period.
What Could Drive a Sustained Recovery
The strongest bullish catalyst for First Solar, Inc. (NASDAQ: FSLR) would be a sequence of results showing that contracted demand is translating into timely deliveries, resilient margins, and dependable earnings. Greater policy clarity and more manageable financing conditions could reinforce that progress.
At approximately 8.3 times forward earnings, the stock’s appeal rests on the possibility that future profits prove more durable than the current valuation suggests. If the company meets earnings expectations and reduces uncertainty around its outlook, investors could become willing to pay a higher multiple.
The investment thesis ultimately rests on execution. A domestic manufacturing base and contracted backlog provide the foundation; profitable deliveries would turn that foundation into a stronger case for the approximately 60.3% potential upside reflected in average analyst targets.
YOU MUST READ THIS: 10 Cheap Stocks Reddit Investors Think Could Skyrocket
Disclosure: No material interests to disclose. This article was originally published on Global Market Bulletin.